Demystifying Roof Claims: How Recoverable Depreciation Actually Works
When a severe storm damages your home, the immediate aftermath is stressful enough. But for many homeowners in Green Country, the real confusion begins when the insurance paperwork arrives in the mail. You might be looking at a multi-page document filled with industry jargon, payout schedules, and a line item that often causes panic: recoverable depreciation.
Seeing that your insurance company is holding back a significant portion of your settlement can be incredibly frustrating. It often leaves families wondering how they will afford the upfront costs of materials and labor. This financial strain is one of the most common concerns we hear from homeowners trying to navigate the recovery process.
At Sacred Ground Properties, our core philosophy is about bringing certainty into a world of uncertainty. We know that dealing with roof damage is disruptive, and worrying about how your insurance claim pays out only adds to that burden. We believe in empowering you with clear, straightforward information. By understanding exactly how recoverable depreciation works, you can approach your upcoming exterior restoration with confidence and peace of mind.
Actual Cash Value vs Replacement Cost Value
To understand recoverable depreciation, we first need to break down how insurance companies calculate the value of your property. If you have a standard homeowner's policy that covers replacement cost, your claim will generally involve two distinct figures: Actual Cash Value (ACV) and Replacement Cost Value (RCV).
The Replacement Cost Value is the total estimated amount it will take to restore your property to its pre-storm condition using materials of similar kind and quality at today's market prices. However, insurance companies do not simply write a check for the full RCV upfront.
Instead, they issue your first payment based on the Actual Cash Value. The ACV is calculated by taking the total replacement cost and subtracting the depreciation of your old materials. Because your roof is exposed to the elements and ages over time, it naturally loses value. If your shingles were rated for thirty years and you are fifteen years into their lifespan, the insurance adjuster will factor that age into their initial payout.
The difference between the total replacement cost and the actual cash value is your recoverable depreciation. Essentially, it is a portion of your approved settlement that the insurance provider sets aside until the work is actually completed. This system is designed to ensure that the funds are used specifically for the intended repairs rather than for other purposes.
Understanding actual cash value vs replacement cost value roofing payouts is essential because it sets the expectation for your cash flow during the project. You will receive an initial check to help get the project started, and the remaining funds will be released later, provided you follow the correct procedures.
The Steps to Releasing Your Depreciation Funds
Many homeowners ask us exactly how recoverable depreciation works roof replacement projects in practice. The short answer is that you have to prove the work was done, and done correctly. Navigating this process alone can be overwhelming, which is why working with an experienced contractor is so important. We provide complete insurance claim assistance to make this process completely stress-free.
Here is a breakdown of how a typical, fully supported claim progresses:
- Damage Evaluation: We start with a thorough property assessment to confirm qualifying storm damage. Today, we utilize modern technology like drone-based roof inspections to capture high-resolution imagery and 3D models, ensuring no hidden damage is overlooked.
- Claim Filing Assistance: If we find sufficient damage, we help you file the initial claim with your insurance carrier.
- Adjuster Meeting: We meet directly with the insurance adjuster on-site. Having a professional advocate present ensures that all damage is properly identified and that both parties agree on a fair repair estimate.
- Dispute Resolution: In the rare event of a disagreement with the insurance carrier, we have the resources to involve public adjusters, engineers, or lawyers to ensure you receive a proper payout.
- Construction Completion: Once the initial ACV check is received and the scope of work is approved, our licensed and insured crews begin your roof replacement, restoring your property to its original condition safely and efficiently.
- Final Documentation: This is the most crucial step for releasing your held-back funds. We compile and submit all necessary final paperwork to the insurance company on your behalf.
Submitting Proof of Completion
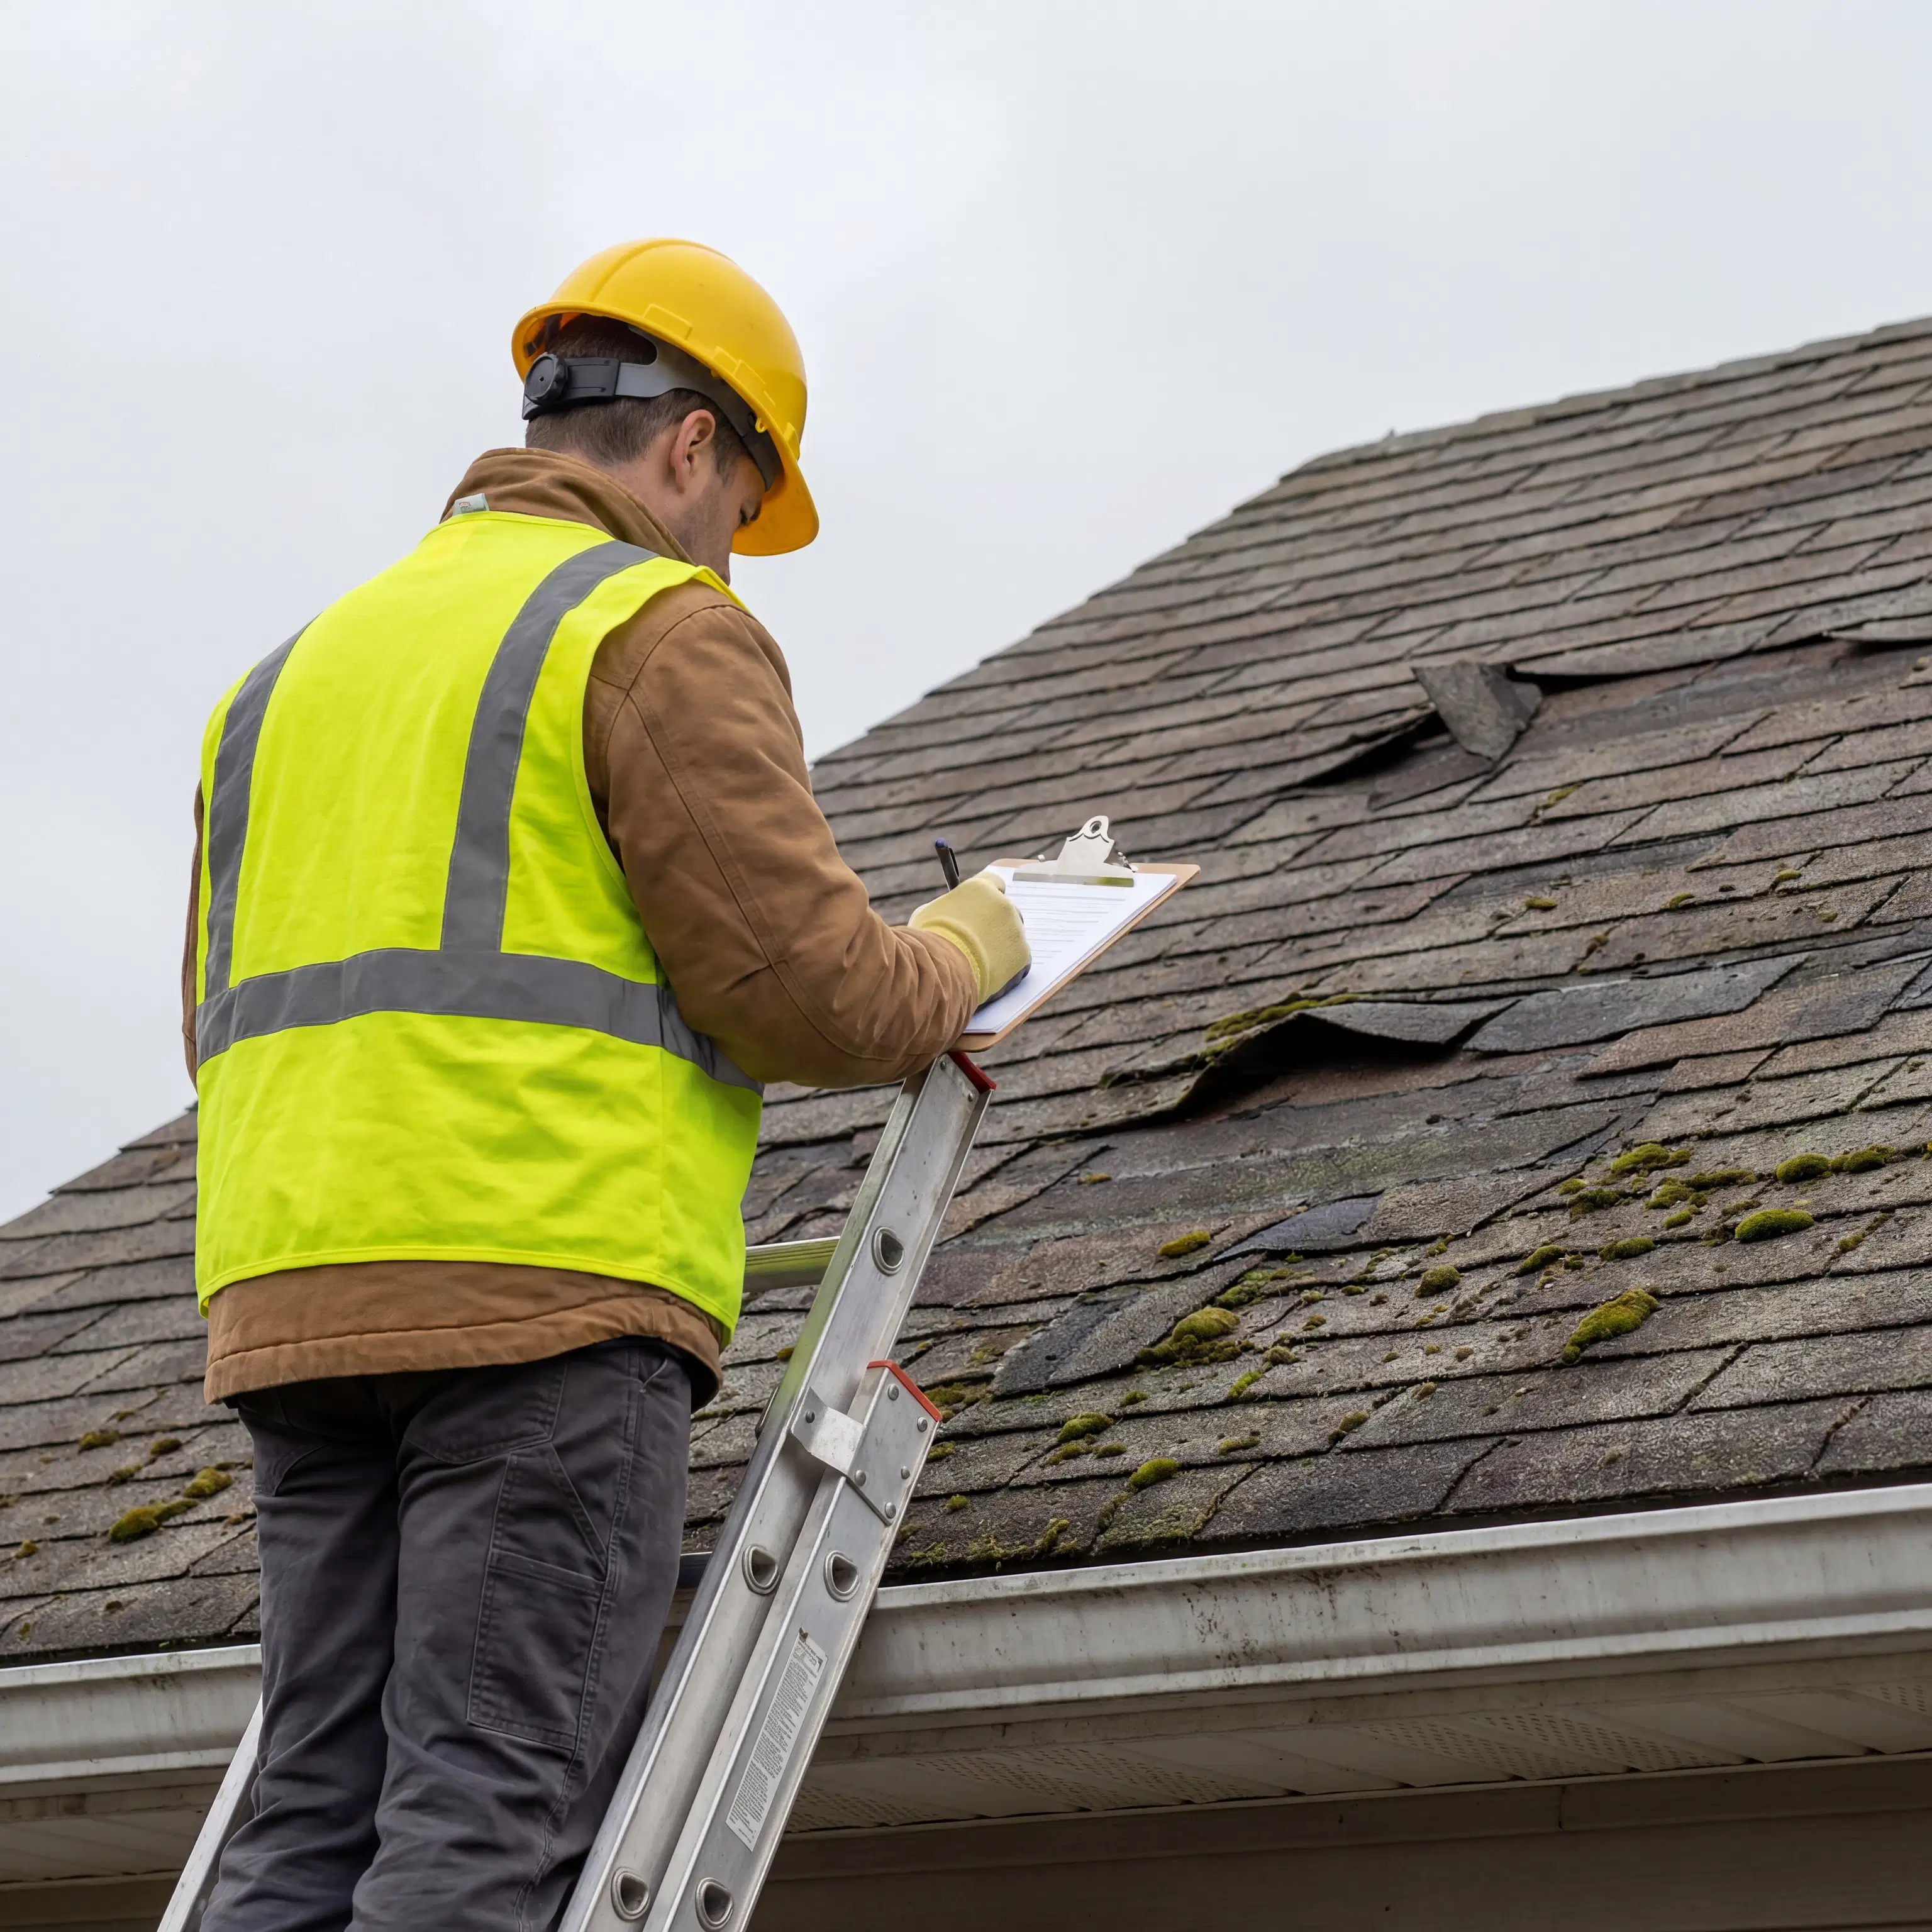
Releasing insurance depreciation funds for roof repair hinges on the final step of the process. Insurance companies require strict documentation before they will disburse the remaining money. They need to verify that the project was finished according to the agreed-upon scope of work and that the total costs align with the estimates.
This involves submitting certificate of completion for roof claim processing, along with final invoices and sometimes photographic evidence of the finished product. If there were any required code upgrades or unexpected material cost fluctuations during the build, those supplements must also be carefully documented and approved.
When you partner with a reputable contractor, you shouldn't have to worry about this administrative headache. Our team handles the invoicing and the submission of all required completion documents directly to your carrier. Once the insurance company reviews and approves the final paperwork, they will issue the second check, which covers the recoverable depreciation. This final check, combined with your initial payout and your required deductible, covers the total cost of your new roof.
Protect Your Investment with the Right Partner
Dealing with the aftermath of a storm in Tornado Alley requires patience, but it shouldn't require you to become an insurance expert overnight. The key to a successful, financially sound restoration is choosing a contractor who understands the intricacies of the claims process just as well as they understand quality craftsmanship. Proper licensing, strong manufacturer warranties, and comprehensive insurance coverage are non-negotiable traits you should look for when hiring a team to protect your home.
At Sacred Ground Properties, we take pride in offering exceptional residential roofing backed by transparent communication from the initial inspection to the final paperwork. If you are dealing with storm damage and need a trusted advocate to help you navigate your claim and recover your depreciation funds, reach out to us today. We are here to bring certainty back to your home.